5 Critical Internal Controls for Owner-Managed Businesses
Owner-managed businesses often run lean, with the owner taking on multiple roles. While this can keep costs low and decision-making fast, it can also create risks if financial controls are weak or overlooked. Internal controls aren’t just for large corporations — they’re essential for safeguarding assets, ensuring accurate records and deterring fraud or errors. Strengthening these key areas of internal control help to ensure your numbers reflect reality, which is critical for making sound business decisions.
1. Segregation of Duties
One of the most important principles is segregation of duties. In small businesses, it’s rarely possible to split every task across multiple employees. However, even simple adjustments can help. For example, the person responsible for recording vendor invoices shouldn’t also be the person writing checks. If staff is limited, the owner can step in to review reconciliations or sign off on unusual transactions.
2. Authorization and Approval Processes
All significant transactions should require some form of approval. This might mean the owner personally signs checks above a certain dollar amount or reviews payroll before funds are released. Documented approval processes reduce the risk of unauthorized spending and also create an audit trail that can be referred to later.
3. Physical and Digital Safeguards
Internal controls also involve protecting physical and digital assets. Locking up blank checks, restricting access to accounting software and regularly updating passwords are basic but powerful measures. For businesses that handle inventory, periodic counts compared to the books can highlight theft, shrinkage or recording errors.
4. Regular Financial Reporting
Producing timely financial reports — monthly or at least quarterly — helps owners spot trends, cash-flow problems or variances from the budget. Reports should be compared against prior periods and expectations, with any discrepancies investigated. Many small business owners rely heavily on their bookkeeper or outside accountant for this process, but the owner’s active involvement is still essential.
5. Reviewing Bank Statements and Transactions
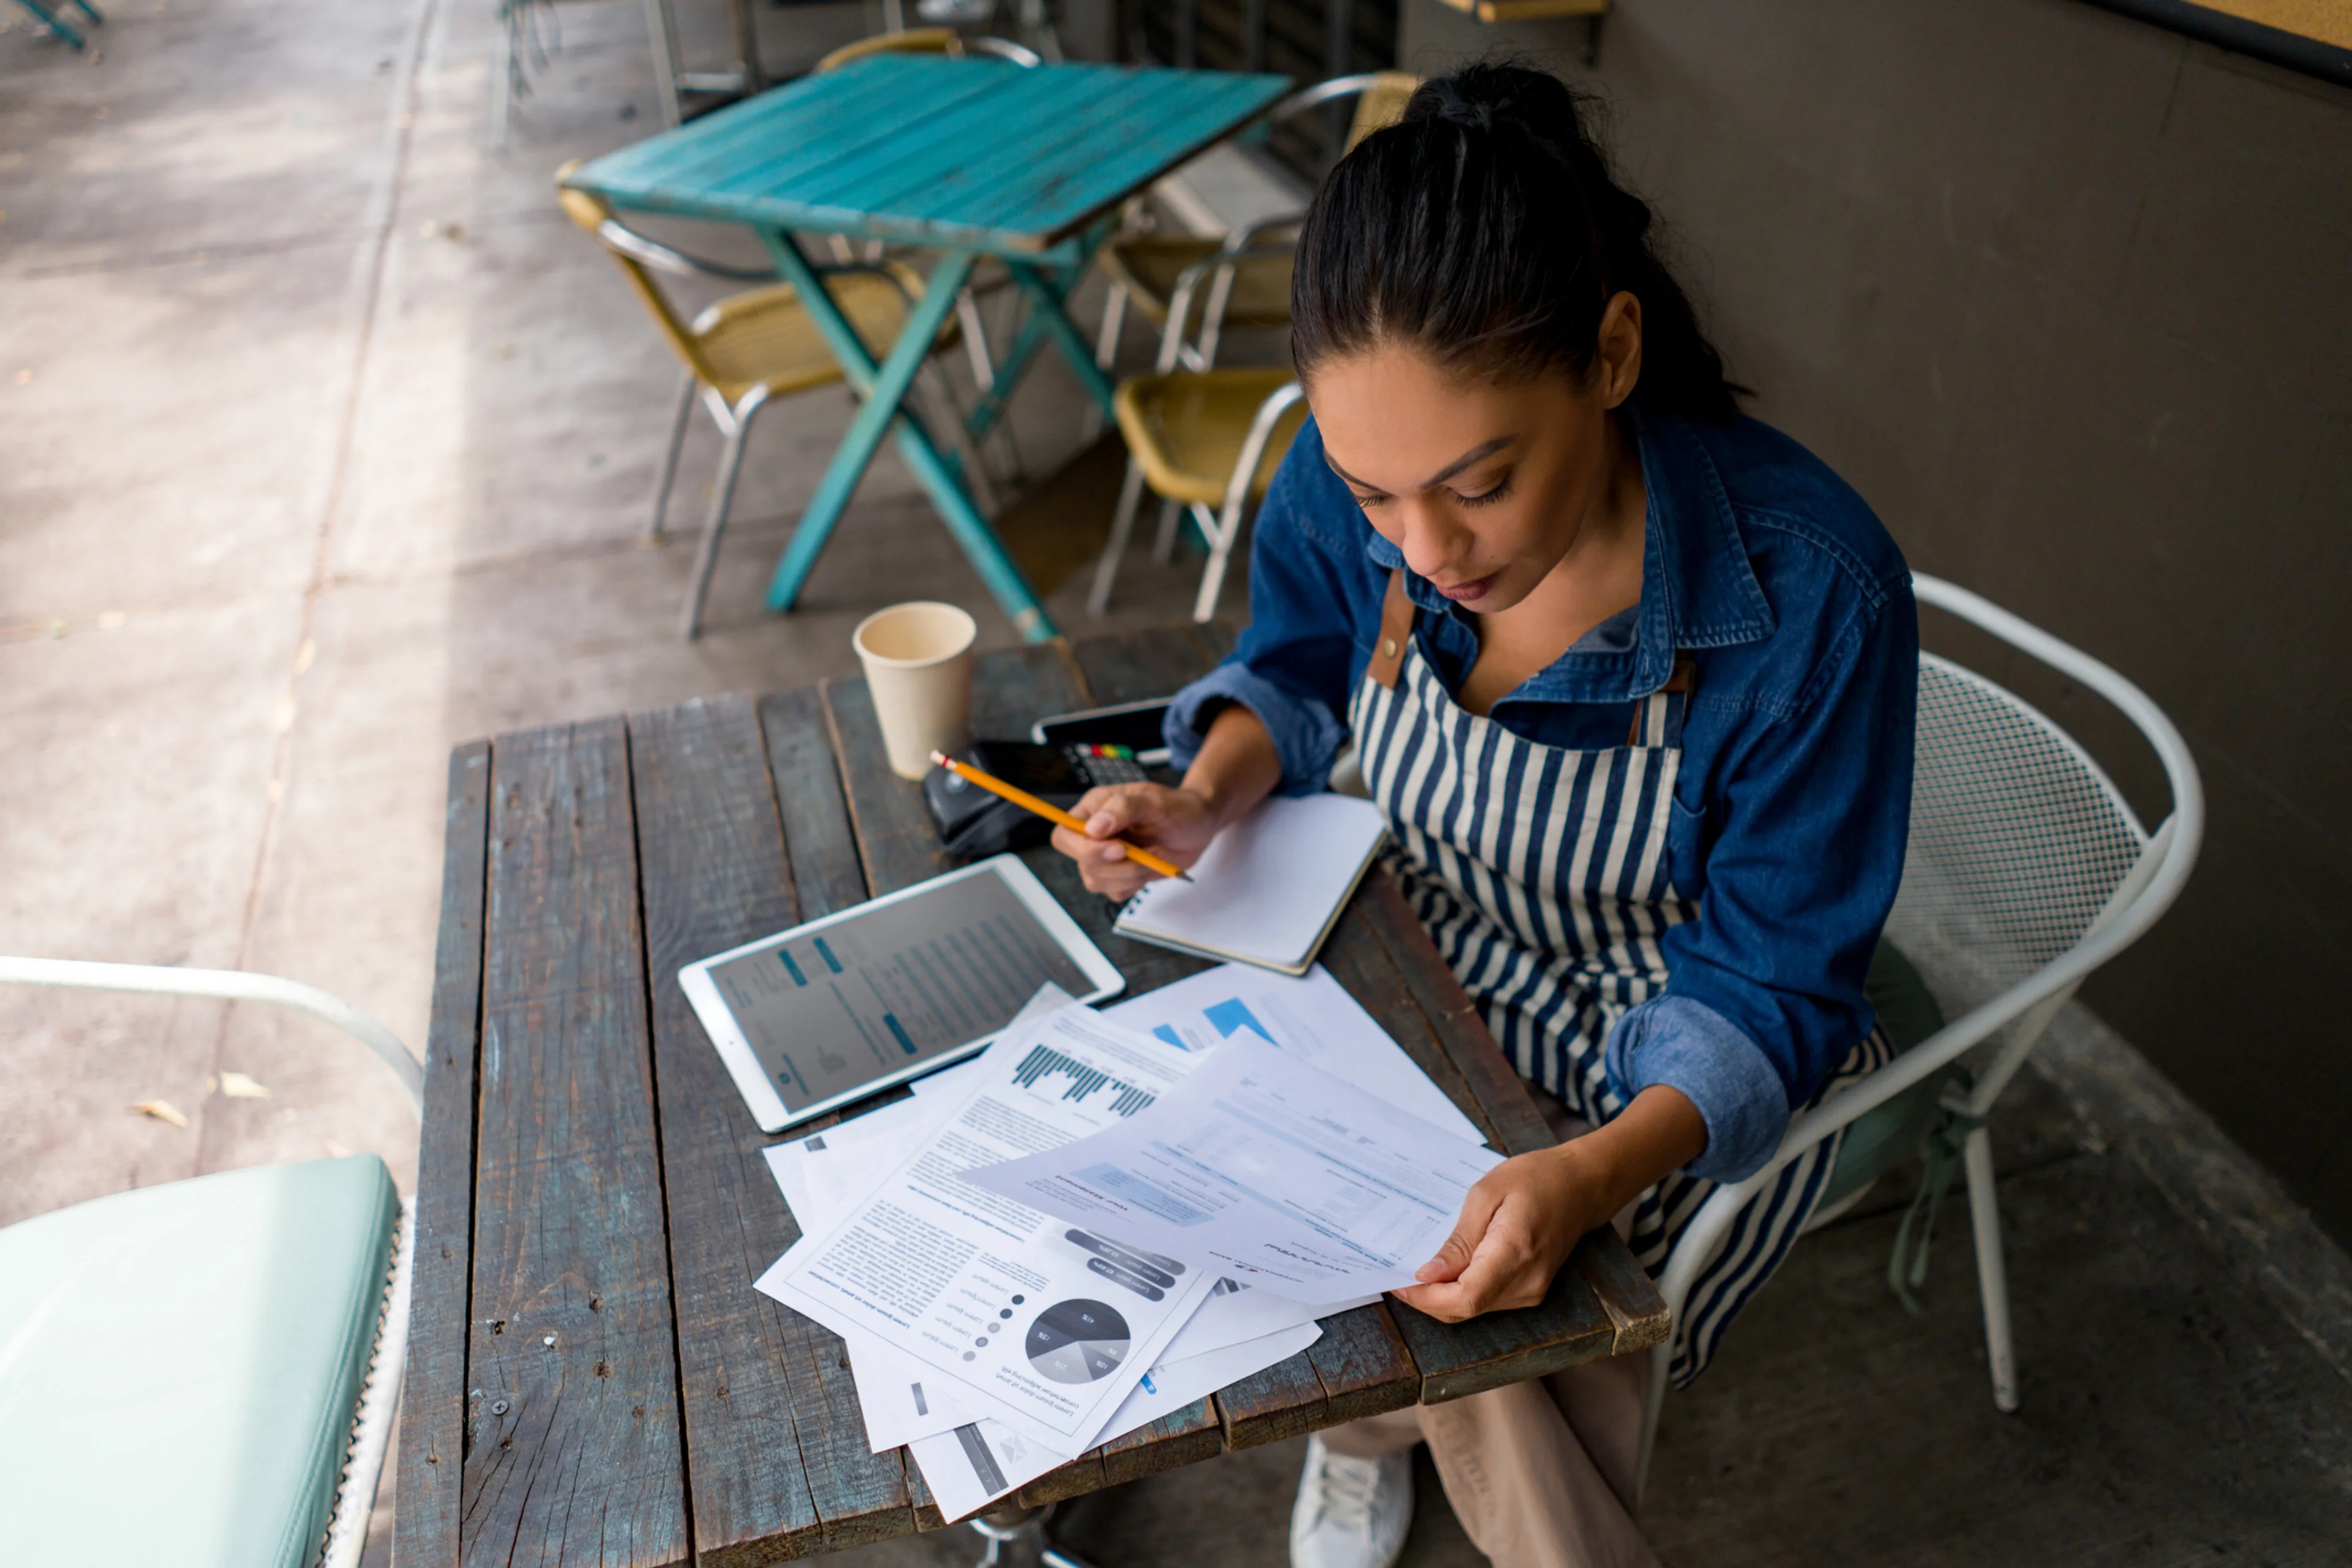
One of the simplest and most effective controls for an owner-managed business is the regular review of bank statements and transactions. The owner should receive bank statements directly from the bank (or access electronically) and compare them to accounting records. This review can reveal unauthorized withdrawals, altered checks or duplicate payments that might otherwise go unnoticed. Ask questions — having everyone know you review is a great deterrent.
Reconciling the bank account monthly ensures that cash balances are accurate and prevents the buildup of errors over time. In addition, scanning individual transactions such as unusual transfers or payments to unknown vendors helps maintain oversight, even if bookkeeping tasks are delegated.
Here to Help
Internal controls aren’t about adding bureaucracy; they’re about creating safeguards that protect both the owner and the business. Even simple steps — segregating duties where possible, requiring approvals, safeguarding assets, generating regular reports, and reviewing bank statements — can significantly reduce risks. Look to our advisors and accounting specialists to help implement and strengthen controls for improved financial integrity, reduced risk and better-informed decisions.